Connecticut Hardware Store Insurance

See How We're Different
or call us: (203) 269-9565
Running a hardware store in Connecticut means stocking thousands of SKUs, from power tools and paint to fasteners and fertilizers, while managing a physical space that sees steady foot traffic year-round. A single customer injury, a burst pipe that ruins inventory, or a
data breach at your point-of-sale terminal can threaten the business you've spent years building. Understanding the insurance coverage a Connecticut hardware store needs, spanning liability, property, auto, cyber, and workers' compensation, isn't just a box-checking exercise. It's the foundation of long-term survival. The right policies protect your assets, your employees, and your customers, while the wrong gaps can turn a manageable incident into a financial catastrophe. Every store's risk profile is a little different depending on size, services offered, and whether you run deliveries, but a core set of coverages applies to nearly every hardware retailer in the state. Here's what you should carry and why each policy matters.
Core Liability Coverage for Connecticut Hardware Retailers
Liability claims are the most common reason hardware store owners file insurance claims. Your store combines heavy merchandise, sharp tools, chemical products, and a public shopping floor, all of which create exposure. Two types of liability coverage form the backbone of your protection.
General Liability: Protecting Against Slip-and-Falls
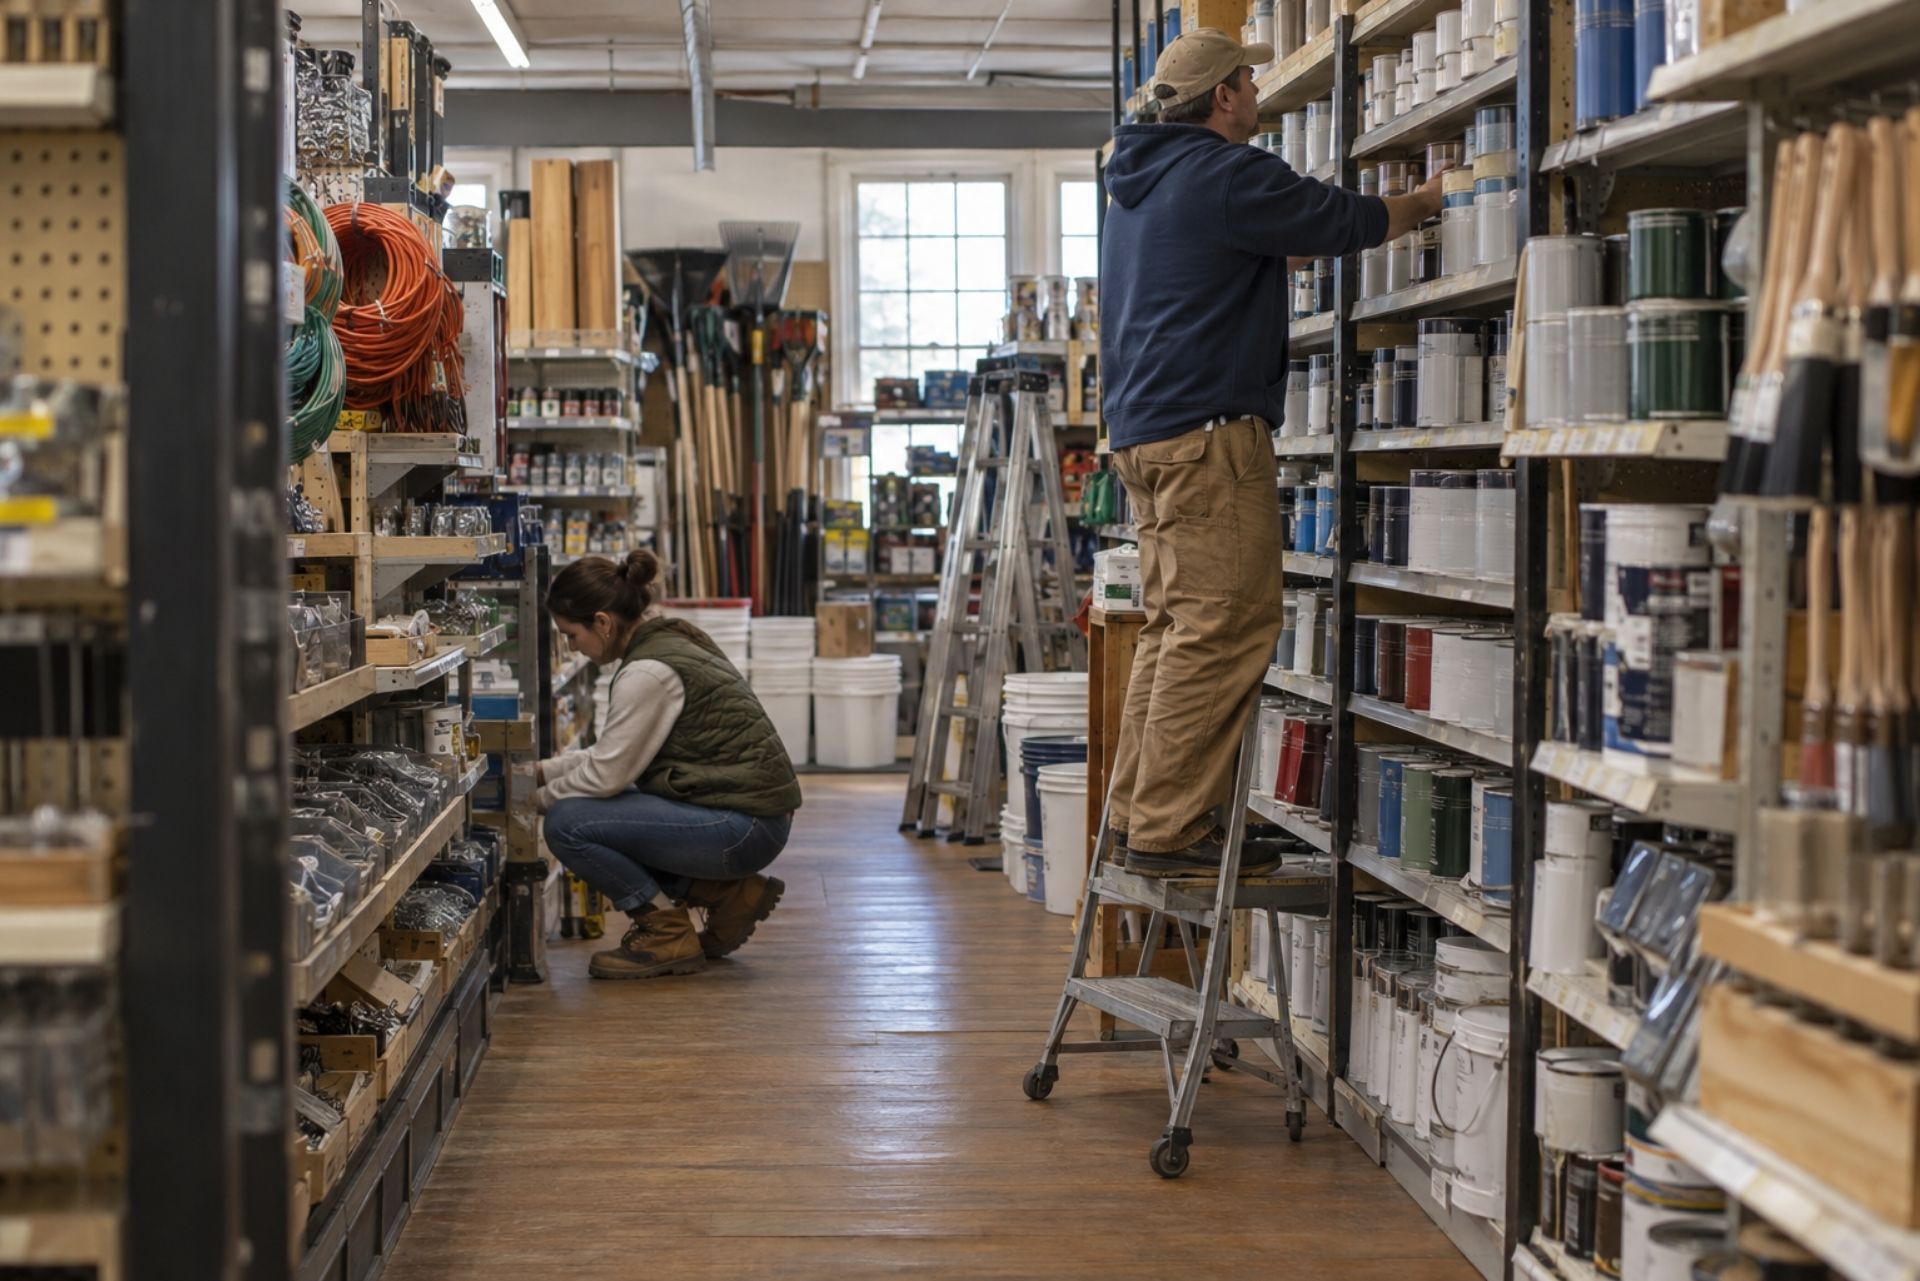
General liability insurance covers bodily injury and property damage claims made by third parties, typically customers or vendors on your premises. A customer who slips on a wet floor near the paint aisle, trips over a pallet in a narrow corridor, or is struck by falling merchandise from a high shelf can file a claim that includes medical bills, lost wages, and legal fees.
For a Connecticut hardware store, a standard general liability policy with $1 million per occurrence and $2 million aggregate is the typical starting point. Stores with higher foot traffic or larger square footage may need higher limits. This policy also covers advertising injury, such as claims of slander or copyright infringement in your marketing materials. A comprehensive hardware store insurance guide can help you identify the specific endorsements that fit your operation.
Product Liability for Tool and Equipment Sales
Selling power tools, electrical components, ladders, and chemicals creates a distinct risk that general liability alone doesn't fully address. Product liability coverage protects you if a product you sold causes injury or property damage after the customer takes it home. If a defective chainsaw injures a homeowner or a faulty electrical fitting causes a house fire, the injured party may sue your store alongside the manufacturer.
Even though the manufacturer typically bears primary responsibility, your store sits in the
distribution chain and can be named in lawsuits. Product liability coverage pays for legal defense and settlements. Hardware stores that sell house-brand or private-label products face higher exposure because the manufacturer may be harder to identify or pursue.
Protecting Your Inventory and Physical Assets
Your building, fixtures, signage, and inventory represent a significant capital investment. A single event, whether fire, storm, or vandalism, can wipe out months of revenue if you're underinsured.
Commercial Property Insurance for High-Value Stock
Commercial property insurance covers your building (if you own it), interior improvements, equipment, and inventory against covered perils like fire, wind, theft, and vandalism. Hardware stores carry dense, high-value inventory. A mid-sized store might hold $300,000 to $800,000 in stock at any given time, and seasonal fluctuations around spring gardening or winter storm prep can push that number higher.
The commercial property insurance market has been adjusting premiums in response to rising replacement costs and increased catastrophe losses, making it essential to review your coverage limits annually. Make sure your policy reflects actual replacement cost rather than depreciated value. Stores that carry flammable products like paint thinners, propane, or solvents should confirm those items are covered, as some policies exclude or limit coverage for hazardous materials.
Business Interruption: Staying Afloat During Repairs
If a covered event forces your store to close temporarily, business interruption insurance replaces lost income and covers ongoing expenses like rent, payroll, and loan payments. This coverage is typically bundled with your commercial property policy but requires careful attention to the waiting period (often 72 hours) and the coverage period (usually 12 months, though extensions are available).
A fire that shuts your store for three months doesn't just cost you the damaged inventory. You lose daily sales, your employees may find other jobs, and loyal customers may shift to competitors. Business interruption coverage bridges that gap. One common mistake store owners make is underestimating their actual revenue when setting coverage limits, so base your figures on recent tax returns rather than rough estimates.
Connecticut State Requirements and Specialized Policies
Connecticut has specific legal requirements that affect your insurance decisions, and several specialized policies address risks unique to retail hardware operations.
Workers' Compensation Laws for CT Small Businesses
Connecticut law requires workers' compensation coverage for all employers, with very few exceptions. If you have even one employee, whether full-time, part-time, or seasonal, you must carry this coverage. It pays for medical treatment, rehabilitation, and a portion of lost wages when an employee is injured on the job. Hardware store injuries often involve lifting heavy materials, cuts from box cutters or saws, falls from ladders, and exposure to chemicals.
The good news for Connecticut employers is that voluntary market loss costs for workers' compensation decreased by 6.1% starting January 1, which may translate to lower premiums depending on your claims history and classification code. That said, your experience modification rate (your "mod") plays a significant role in your actual premium. Stores with strong safety programs and few claims can see rates well below the baseline.
Commercial Auto for Delivery and Rental Vehicles
If your store offers delivery services, picks up inventory from suppliers, or operates any vehicles under the business name, you need commercial auto insurance. Personal auto policies don't cover vehicles used for business purposes, and a serious accident during a delivery could expose your store to substantial liability.
Commercial auto policies cover liability, collision, comprehensive damage, and uninsured/underinsured motorist protection for your business vehicles. If employees use their personal cars for store errands or deliveries, a hired and non-owned auto endorsement fills that gap. Stores that rent trucks seasonally for large deliveries should confirm their policy covers rented vehicles as well.
Cyber Liability: Securing POS Systems and Customer Data
Hardware stores process credit and debit card transactions daily, and many now maintain customer databases for loyalty programs, contractor accounts, and online ordering. A data breach that exposes customer payment information can trigger notification costs, credit monitoring obligations, regulatory fines, and lawsuits.
Connecticut's Data Privacy Act has been actively enforced, with the state attorney general
releasing updated enforcement reports that signal increased scrutiny of how businesses handle consumer data.
Cyber liability insurance covers breach response costs, forensic investigation, customer notification, legal defense, and regulatory penalties. Even a small hardware store with a single POS terminal faces this risk. The
2025 CTDPA enforcement report showed that businesses of all sizes were subject to investigation, not just large retailers.
Comparing Essential vs. Optional Coverages
Not every policy carries the same urgency. The table below breaks down what's required, what's strongly recommended, and what's situational for a typical Connecticut hardware store.
| Coverage Type | Required? | Typical Limit | Who Needs It |
|---|---|---|---|
| General Liability | Strongly recommended (often required by landlords) | $1M per occurrence / $2M aggregate | Every hardware store |
| Product Liability | Strongly recommended | Included in GL or separate $1M+ | Stores selling tools, chemicals, electrical |
| Commercial Property | Strongly recommended | Based on replacement cost | Store owners and tenants with inventory |
| Business Interruption | Strongly recommended | 12 months of revenue | Any store that can't afford downtime |
| Workers' Compensation | Required by CT law | Statutory limits | All employers with 1+ employees |
| Commercial Auto | Required if business vehicles are used | $1M combined single limit | Stores with delivery or pickup services |
| Cyber Liability | Optional but strongly recommended | $100K to $1M | Stores processing card payments |
| Umbrella/Excess | Optional | $1M to $5M | Stores wanting extra protection above primary limits |
| Employment Practices Liability | Optional | $500K to $1M | Stores with 5+ employees |
An
umbrella policy is worth considering if your store has significant assets to protect. It sits above your general liability, auto, and employer's liability limits, kicking in when a claim exceeds those primary caps. For a store with $2 million in annual revenue and substantial inventory, an umbrella policy of $1 million to $3 million is a reasonable investment.
Common Questions About Hardware Store Insurance
How much does insurance cost for a small hardware store in Connecticut? A typical small hardware store can expect to pay between $3,000 and $8,000 annually for a business owner's policy (BOP) that bundles general liability and commercial property. Workers' comp, auto, and cyber are priced separately based on payroll, vehicles, and data exposure.
Can I bundle my policies to save money? Yes. A BOP combines general liability and commercial property into a single policy at a lower premium than purchasing them separately. Many insurers offer additional discounts when you add auto or umbrella coverage to the same account.
Do I need product liability if I only sell name-brand products? You should still carry it. As a retailer in the distribution chain, you can be named in a lawsuit even if the defect originated with the manufacturer. Defense costs alone can be significant.
Is cyber insurance really necessary for a small store? If you accept credit cards, store customer information, or operate any digital systems, yes. A single breach can cost tens of thousands of dollars in notification and remediation, even for a small operation.
What happens if I don't carry workers' comp in Connecticut? You face fines, potential criminal penalties, and personal liability for any employee injuries. The state takes enforcement seriously, and uninsured employers can be shut down.
Does my landlord's insurance cover my inventory?
No. Your landlord's policy covers the building structure, not your stock, fixtures, or business income. You need your own commercial property policy for those assets.
Making the Right Choice for Your Store
The insurance needs of a Connecticut hardware store touch nearly every risk category: customer injuries, product defects, property damage, vehicle accidents, data breaches, and employee injuries on the job. Skipping any one of these coverages creates a gap that could cost far more than the premium you saved.
Start by getting your workers' compensation and general liability policies in place, since those address your most immediate legal and financial exposures. From there, build out your commercial property, auto, and cyber coverage based on your store's specific operations. Review your policies annually, especially your property limits, to keep pace with inventory growth and replacement costs.
Talk to an independent agent who works with retail or hardware accounts. They'll understand the nuances of your classification codes, your product mix, and the Connecticut-specific requirements that affect your premiums. The right coverage isn't about buying the most insurance: it's about buying the right insurance for the risks your store actually faces.
About The Author:
John F. McGuire
As President of Ferguson & McGuire, I’m committed to helping families and businesses throughout Connecticut find insurance solutions they can trust. With decades of experience in the industry, my focus is on providing personal service, reliable protection, and long-term peace of mind for every client we serve.
GET A QUOTE POPUP
TESTIMONIALS
Business Insurance Client Stories
Business Insurance Solutions in Connecticut
Tailored Assessments for Businesses
We delve into the intricacies of your business operations and insurance requirements, focusing on the specific challenges and opportunities presented by the Connecticut business landscape. Our aim is to identify comprehensive coverage strategies that fully protect your business interests.
Customized Commercial Insurance Solutions
With a keen eye on the unique needs of Connecticut businesses, we craft insurance solutions that precisely match your requirements. Our process is centered around developing the perfect insurance plan that aligns with your business goals and challenges.
Efficient Policy Setup & Ongoing Support
Initiate your selected insurance coverage swiftly, backed by our dedication to offer continuous support for any questions, claims, or adjustments needed. We are committed to keeping you informed and secure, ensuring your business is always prepared and protected.
Commercial Insurance Coverage in Connecticut
General Liability Insurance
Designed for Connecticut businesses, our General Liability Insurance provides essential protection against claims of bodily injury, property damage, and more, ensuring your business is defended against various liabilities.
Workers Compensation Insurance
Tailored for Connecticut businesses, Workers Compensation Insurance covers employee injuries or illnesses occurring on the job, protecting both your employees and your business's financial health.
Professional Liability Insurance
Our Professional Liability Insurance for Connecticut professionals offers extended coverage to protect against claims of negligence or errors in services provided, securing your professional reputation.
Business Owner's Policy (BOP) Insurance
Perfect for Connecticut businesses, our BOP Insurance merges property and liability coverage into a single policy, providing comprehensive protection for your business operations and assets against a multitude of risks.
Cyber Liability Insurance
Aimed at Connecticut businesses in the digital realm, our Cyber Liability Insurance covers risks associated with data breaches, cyber-attacks, and other online threats, ensuring your business's digital assets are protected.
Data Breach Insurance
Specifically for businesses in Connecticut dealing with sensitive information, our Data Breach Liability Insurance offers vital coverage for incidents of data loss or theft, giving you peace of mind in handling digital data.
OUR SERVICES
Explore Our Wide Range of Tailored Insurance Services
FAQs about a credible Connecticut Business Insurance Agency
All About CT Business Insurance: Your Queries Answered
Connecticut Businesses We Serve
Contractor Insurance
Our Contractor Insurance in Connecticut provides General Liability coverage, essential for defending against bodily injury and property damage claims, crucial for your contracting business's resilience and operational continuity.
Bar Insurance
Customized for Connecticut bars, our insurance solutions include Workers Compensation, ensuring employees are covered and your establishment's financial health is maintained in case of job-related injuries or illnesses.
Auto Body Insurance
Connecticut auto body shops benefit from our General Liability Insurance, offering protection against claims of bodily injury and property damage, vital for your business's reputation and financial stability.
Engineers Insurance
Engineers Insurance in Connecticut encompasses Workers Compensation coverage, providing your employees and engineering firm with financial protection against the consequences of workplace injuries or illnesses.
Electricians Insurance
For electricians in Connecticut, our General Liability Insurance is designed to cover occupational risks, including bodily injury and property damage claims, ensuring your business's smooth operation and security.
HVAC Contractors Insurance
HVAC contractors in Connecticut have access to our comprehensive insurance solutions, including Workers Compensation, which covers employee-related injuries or illnesses, maintaining your workforce's well-being and your business's financial health.
Ready to Get Your Business Insured?
Contact Us