Objective: This guide outlines the policies a Connecticut flower shop should carry, which ones the state requires, and where owners most often leave coverage gaps.
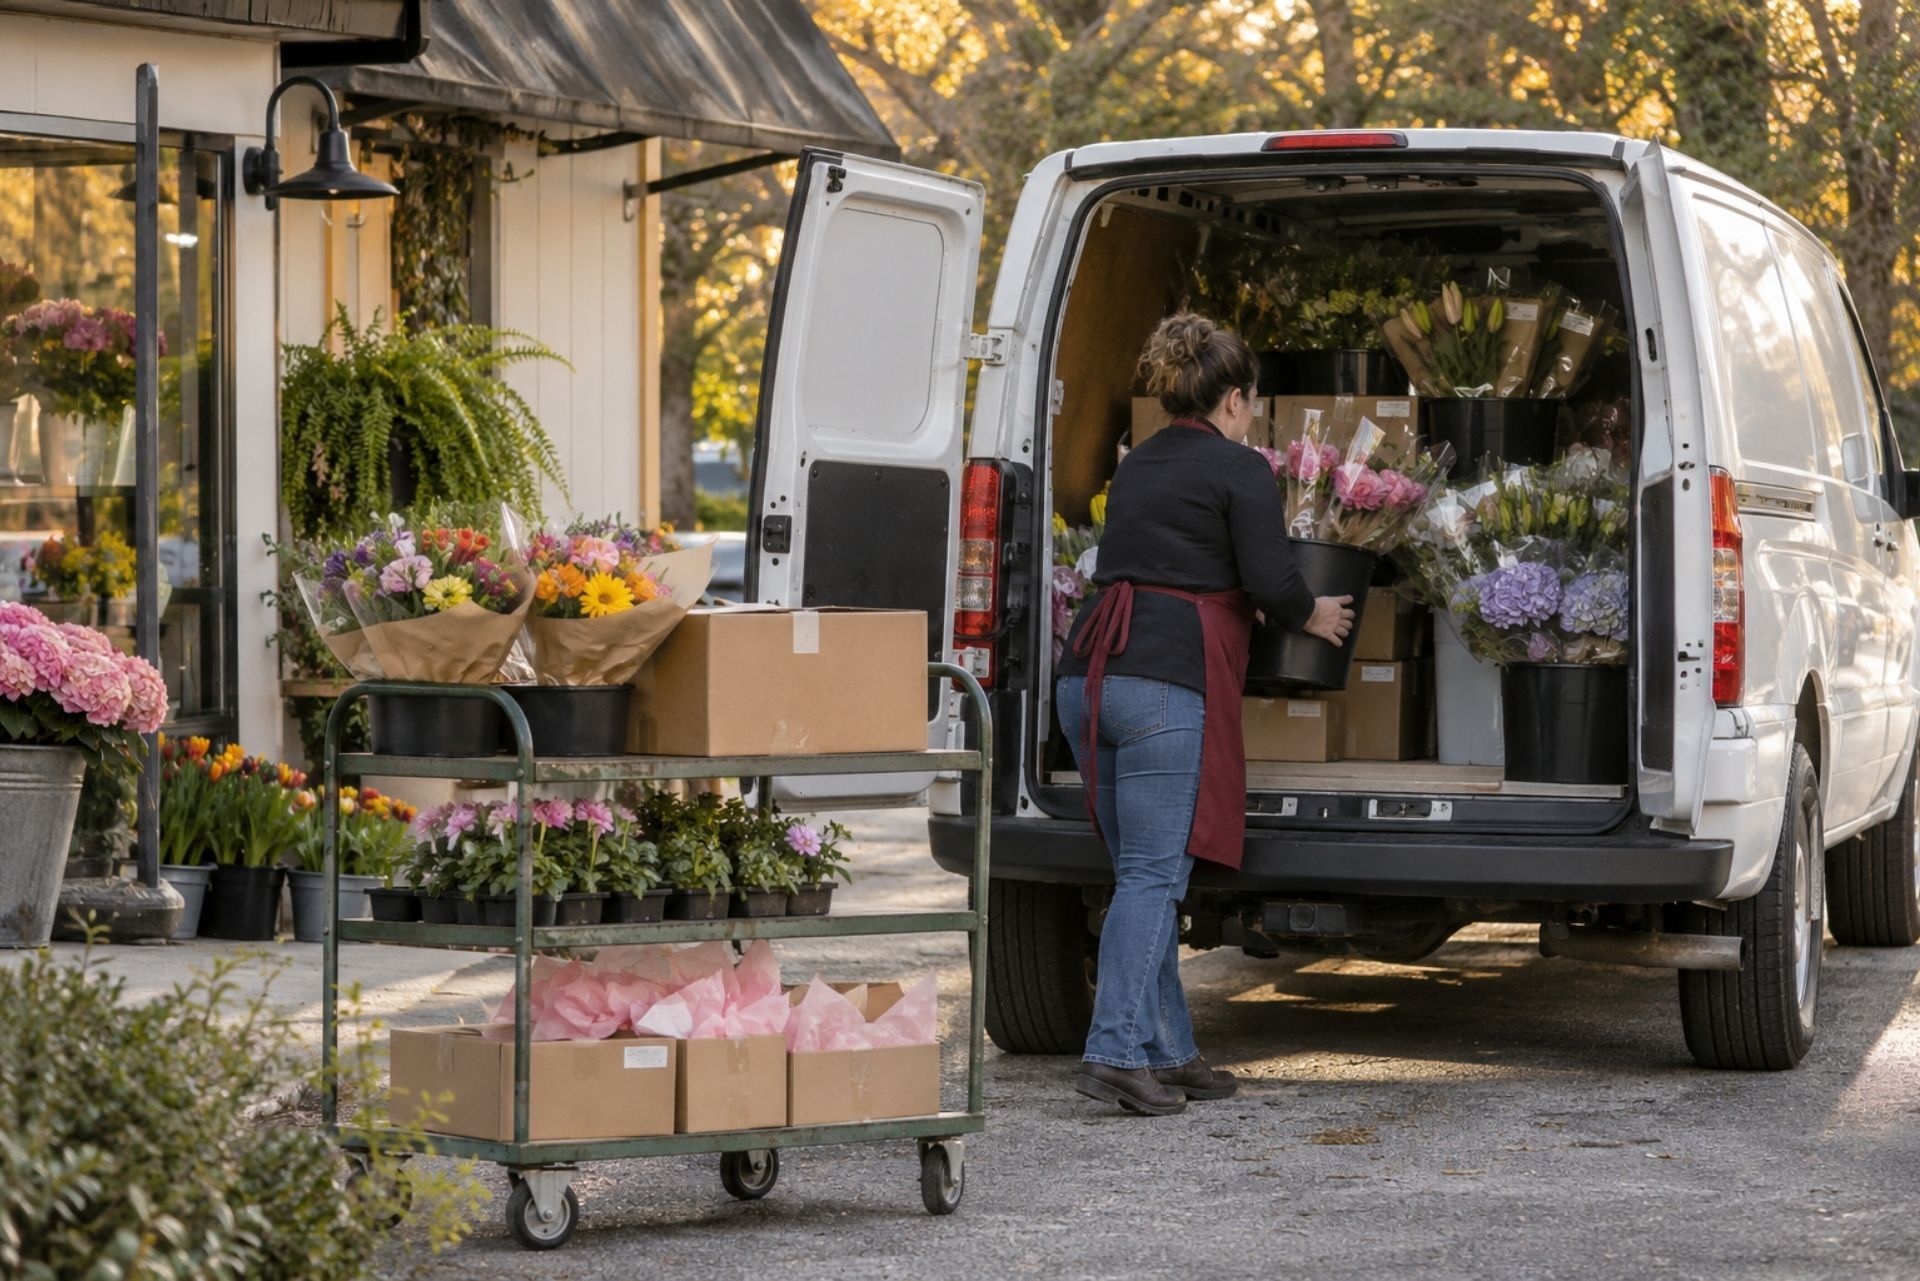
A delivery van slides on black ice in Fairfield County two days before Valentine's Day. A walk-in cooler fails overnight and spoils $8,000 in roses. A customer slips on wet stems near your design counter. Each of these is a routine claim for a florist, and each can be devastating without the right policy. Knowing what insurance a Connecticut florist needs means looking past a single "business policy" and building coverage around how your shop operates: perishable stock, delivery routes, seasonal staff, and online orders. The sections below break down each coverage line so you can review your current policies with a clear eye.
Core Liability Protections for Connecticut Floral Shops
Liability coverage pays when someone outside your business claims you hurt them, damaged their property, or cost them money. For florists, those claims come from foot traffic, event venues, and the arrangements themselves.
General Liability and Product Risks
General liability (GL) covers bodily injury and property damage to third parties. The classic florist claim is a slip on water or fallen petals near a display cooler. Venue damage is another: a heavy centerpiece scratches a reception hall's antique table, or a water-filled vase leaks onto a client's hardwood floor.
Product liability, usually included in GL, matters more than many owners realize. A customer may suffer an allergic reaction, or a pet may ingest a toxic lily you delivered. Standard florist policies typically provide limits of $1 million per occurrence and $2 million aggregate, which many wedding venues and corporate clients require before you can work on site.
Comparing General Liability vs. Professional Liability
GL doesn't cover mistakes in the service itself. If you deliver the wrong arrangements to a high-profile wedding or miss a funeral delivery deadline, the client's financial complaint falls under professional liability, also called an E&O policy.
| Feature | General Liability | Professional Liability (E&O) |
|---|---|---|
| Covers | Injuries, property damage | Service errors, missed deadlines |
| Typical florist claim | Customer slips in shop | Wrong flowers at a wedding |
| Required by venues? | Often | Rarely |
| Who needs it most | Every shop | Event and wedding florists |
If events make up a large share of your revenue, E&O is worth the added premium.
Safeguarding Your Inventory, Equipment, and Data
Your inventory has a shelf life measured in days, and your equipment keeps it alive. That combination makes property coverage for florists different from coverage for a standard retailer.
Commercial Property and Cyber Insurance Needs
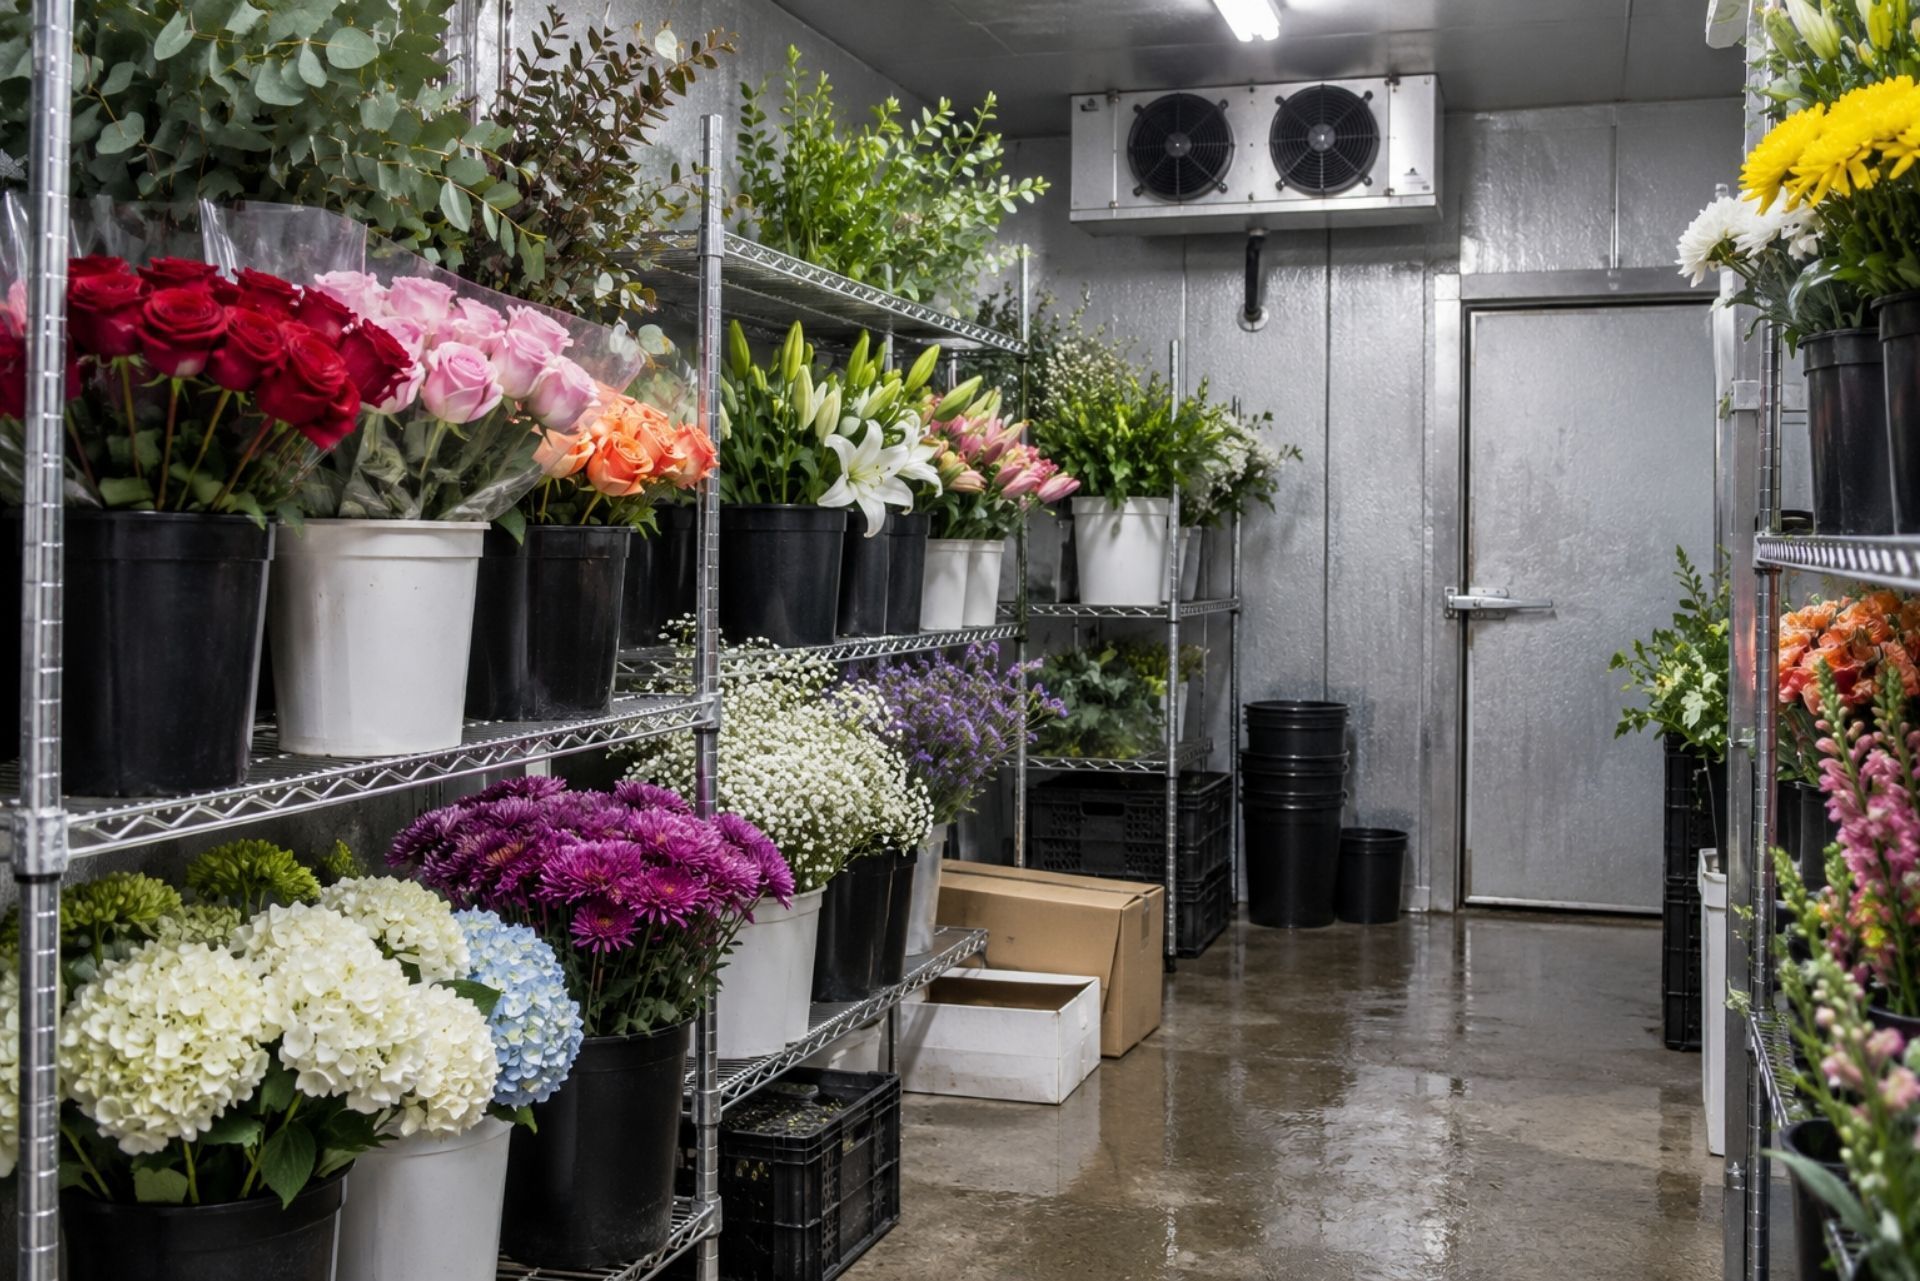
Commercial property insurance covers your building (if you own it), coolers, design tables, POS systems, and stock against fire, theft, and certain weather events. The common gap is spoilage. A basic property form may not pay for flowers lost to a cooler breakdown or power outage, so ask specifically about equipment breakdown and spoilage endorsements. Utility interruption loss of income coverage is another option that helps if you can't operate because water or electricity is cut off, a real risk during Connecticut nor'easters.
Many shops bundle GL, property, and business interruption into a Business Owner's Policy. Bundling these lines typically saves Connecticut florists between 9% and 11% compared with buying them separately.
Cyber coverage has tightened. If you take online orders or store customer card data, carriers now expect documented safeguards. As of 2026, Connecticut small retailers
must show "proof of controls," including Multi-Factor Authentication and Endpoint Detection & Response, to qualify for cyber liability renewals. Set up MFA on your email and order platform before your renewal date, not after.
Connecticut State Requirements: Auto and Workers' Comp
These two lines are where the state steps in, and where florists most often discover they're underinsured.
Connecticut requires liability coverage on every registered vehicle. The catch is that a personal auto policy typically excludes regular business use, including deliveries. If your driver rear-ends someone while dropping off sympathy arrangements in a personal car, the claim may be denied. A commercial auto policy covers shop-owned vans. If employees use their own cars, hired and non-owned auto coverage fills that gap. One market note: on October 23, 2026, several major carriers filed for rate decreases in personal auto and homeowners lines, which may signal some broader cooling, though commercial auto pricing follows its own trends.
Workers' compensation is mandatory in Connecticut for employers with even one employee, including part-time and seasonal holiday help. Florist injuries are predictable: knife cuts, thorn punctures, back strains from lifting buckets, and delivery accidents. Benefit levels also rise each year. As of October 1, 2026, the maximum weekly compensation rate for total disability is $1,776.00, with partial disability capped at $1,175.00. Higher benefit caps can influence what carriers charge, so report payroll accurately to avoid a surprise audit bill.
Critical don'ts checklist:
- Don't let staff make deliveries in personal cars without non-owned auto coverage.
- Don't classify seasonal helpers as contractors to skip workers' comp.
- Don't assume your BOP covers spoiled inventory.
- Don't
wait until renewal week to document cyber controls.
Common Questions About Florist Insurance
Do I need insurance if I run a home-based flower business in Connecticut? Yes. Homeowners policies usually exclude business activity, so inventory, client injuries, and deliveries are likely uncovered.
Does general liability cover flowers that die before an event? No. That's a property or spoilage issue, or an E&O claim if the client says you failed to deliver as promised.
Is workers' comp required if I only hire help for Mother's Day? Yes. Connecticut requires coverage for employees regardless of how short their employment is.
Can I get help covering employee health insurance? Possibly. Florists with 50 or fewer employees may qualify for a state tax credit of up to $1,000 per employee per year, but the business must offer an Individual Coverage Health Reimbursement Arrangement through Access Health CT's BusinessPlus platform.
What happens if my cyber renewal is denied? You'd lose protection against breaches and ransomware. Setting up MFA and endpoint security typically resolves most underwriting objections.
Making the Right Choice for Your Flower Shop
The right insurance package for a Connecticut florist starts with the state mandates, workers' comp and auto liability, then builds outward based on your actual risk. A walk-in retail shop needs strong GL and spoilage coverage. An event-heavy studio needs E&O and venue-friendly certificates. Any shop taking online orders needs documented cyber controls.
Here's what that means for you: pull your current policies this week and check three things. Confirm that deliveries are covered under a commercial or non-owned auto policy, that your property form includes spoilage, and that every employee is on your workers' comp payroll. Then ask your agent to quote a BOP to see whether bundling lowers your premium.
Flowers are temporary. A denied claim isn't. Review your coverage before your busiest season, not after it.
About The Author:
John F. McGuire
As President of Ferguson & McGuire, I’m committed to helping families and businesses throughout Connecticut find insurance solutions they can trust. With decades of experience in the industry, my focus is on providing personal service, reliable protection, and long-term peace of mind for every client we serve.
GET A QUOTE POPUP
TESTIMONIALS
Business Insurance Client Stories
Business Insurance Solutions in Connecticut
Tailored Assessments for Businesses
We delve into the intricacies of your business operations and insurance requirements, focusing on the specific challenges and opportunities presented by the Connecticut business landscape. Our aim is to identify comprehensive coverage strategies that fully protect your business interests.
Customized Commercial Insurance Solutions
With a keen eye on the unique needs of Connecticut businesses, we craft insurance solutions that precisely match your requirements. Our process is centered around developing the perfect insurance plan that aligns with your business goals and challenges.
Efficient Policy Setup & Ongoing Support
Initiate your selected insurance coverage swiftly, backed by our dedication to offer continuous support for any questions, claims, or adjustments needed. We are committed to keeping you informed and secure, ensuring your business is always prepared and protected.
Commercial Insurance Coverage in Connecticut
General Liability Insurance
Designed for Connecticut businesses, our General Liability Insurance provides essential protection against claims of bodily injury, property damage, and more, ensuring your business is defended against various liabilities.
Workers Compensation Insurance
Tailored for Connecticut businesses, Workers Compensation Insurance covers employee injuries or illnesses occurring on the job, protecting both your employees and your business's financial health.
Professional Liability Insurance
Our Professional Liability Insurance for Connecticut professionals offers extended coverage to protect against claims of negligence or errors in services provided, securing your professional reputation.
Business Owner's Policy (BOP) Insurance
Perfect for Connecticut businesses, our BOP Insurance merges property and liability coverage into a single policy, providing comprehensive protection for your business operations and assets against a multitude of risks.
Cyber Liability Insurance
Aimed at Connecticut businesses in the digital realm, our Cyber Liability Insurance covers risks associated with data breaches, cyber-attacks, and other online threats, ensuring your business's digital assets are protected.
Data Breach Insurance
Specifically for businesses in Connecticut dealing with sensitive information, our Data Breach Liability Insurance offers vital coverage for incidents of data loss or theft, giving you peace of mind in handling digital data.
OUR SERVICES
Explore Our Wide Range of Tailored Insurance Services
FAQs about a credible Connecticut Business Insurance Agency
All About CT Business Insurance: Your Queries Answered
Connecticut Businesses We Serve
Contractor Insurance
Our Contractor Insurance in Connecticut provides General Liability coverage, essential for defending against bodily injury and property damage claims, crucial for your contracting business's resilience and operational continuity.
Bar Insurance
Customized for Connecticut bars, our insurance solutions include Workers Compensation, ensuring employees are covered and your establishment's financial health is maintained in case of job-related injuries or illnesses.
Auto Body Insurance
Connecticut auto body shops benefit from our General Liability Insurance, offering protection against claims of bodily injury and property damage, vital for your business's reputation and financial stability.
Engineers Insurance
Engineers Insurance in Connecticut encompasses Workers Compensation coverage, providing your employees and engineering firm with financial protection against the consequences of workplace injuries or illnesses.
Electricians Insurance
For electricians in Connecticut, our General Liability Insurance is designed to cover occupational risks, including bodily injury and property damage claims, ensuring your business's smooth operation and security.
HVAC Contractors Insurance
HVAC contractors in Connecticut have access to our comprehensive insurance solutions, including Workers Compensation, which covers employee-related injuries or illnesses, maintaining your workforce's well-being and your business's financial health.
Ready to Get Your Business Insured?
Contact Us