Connecticut Party and Tent Rental Company Insurance

See How We're Different
or call us: (203) 269-9565
Objective: This guide explains which policies a Connecticut party and tent rental business needs, where the common coverage gaps sit, and how state rules shape your insurance decisions in 2026.
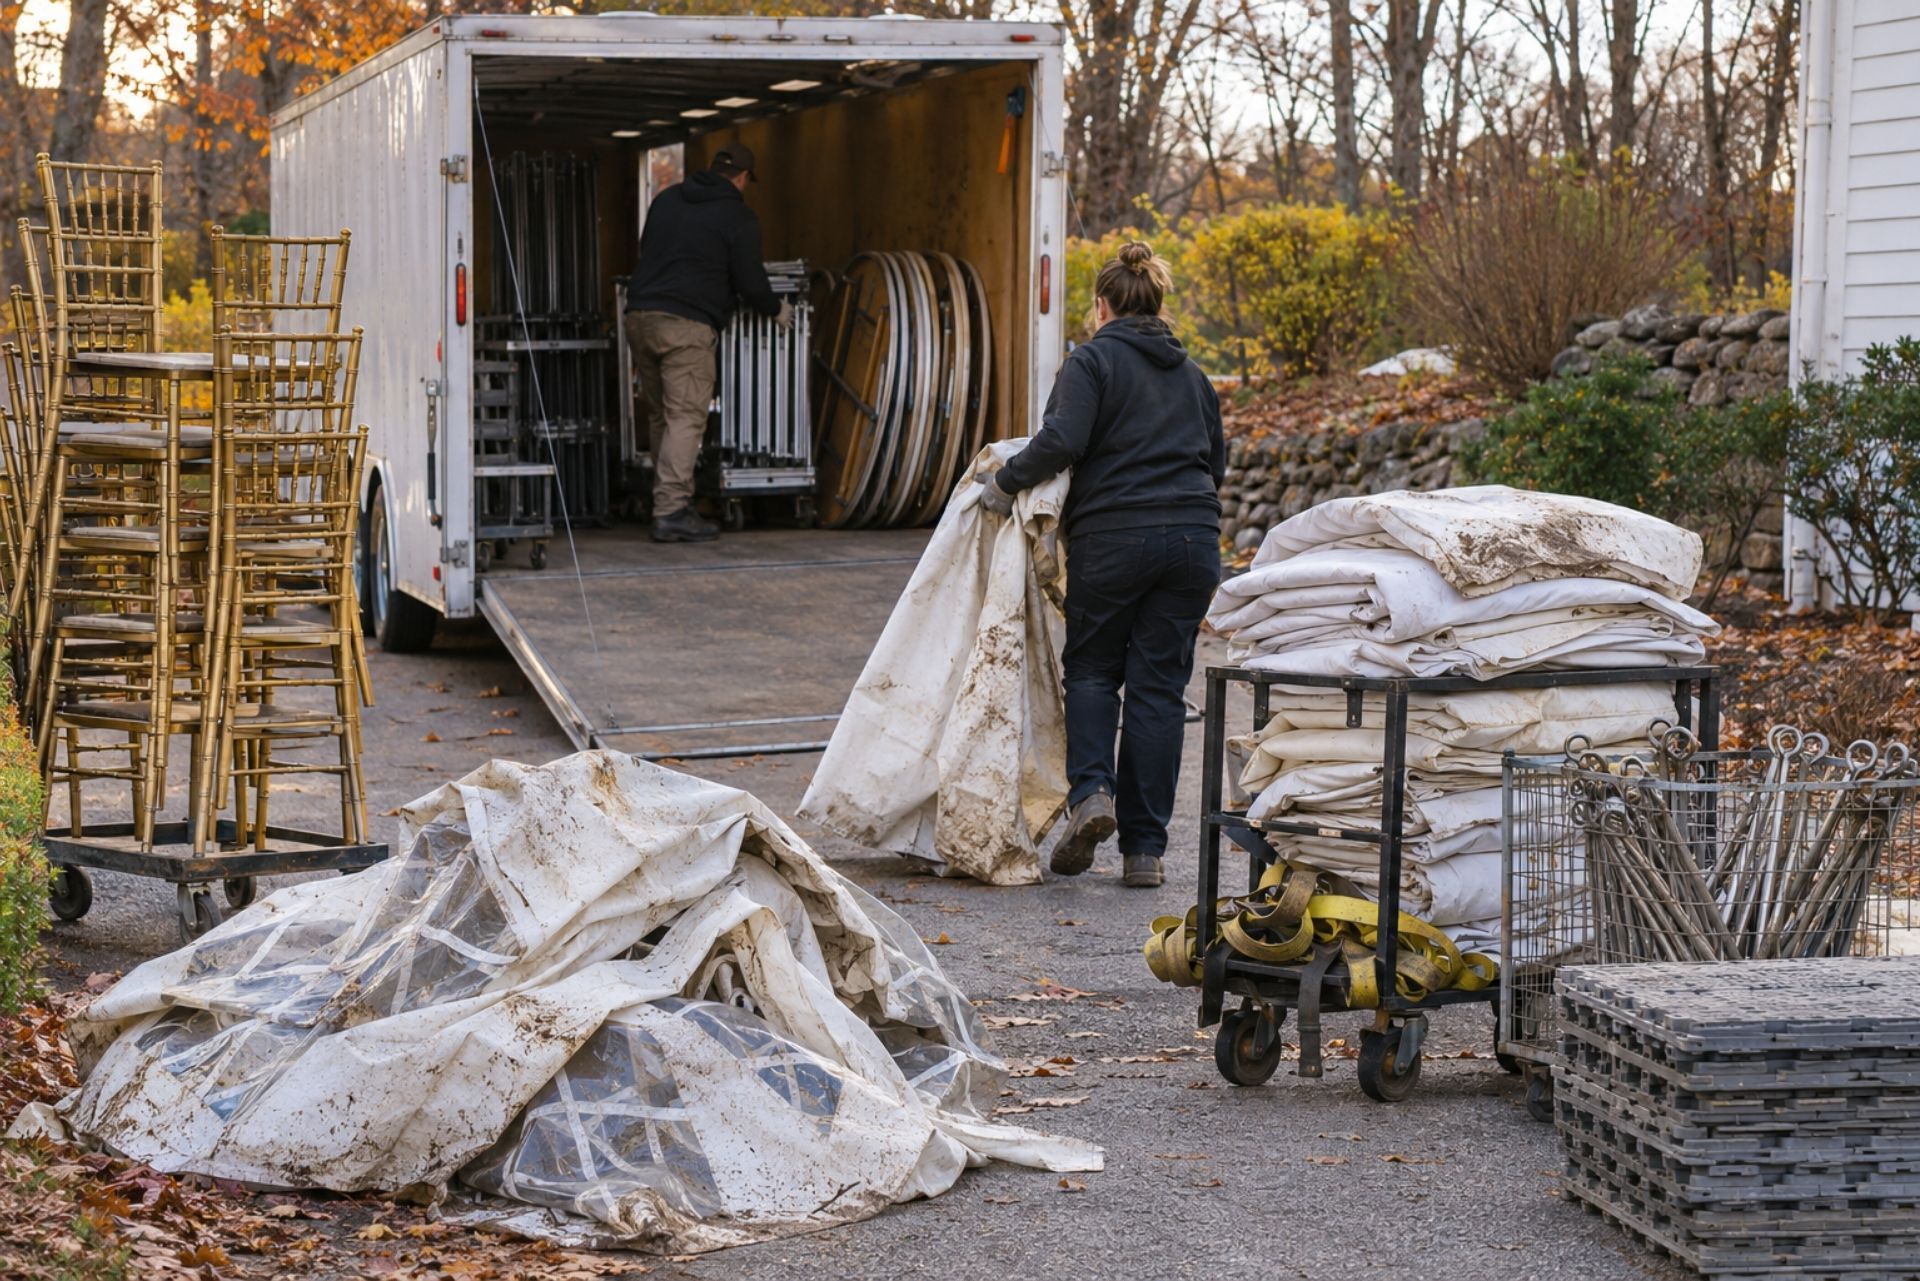
A 40-by-80 frame tent goes up on a Saturday morning in Madison. By late afternoon, a squall line rolls off Long Island Sound. One anchor fails, a guest is hurt, and the tent fabric shreds against a stone wall. Within a single weekend you could face a bodily injury suit, a five-figure equipment loss, and a cancelled booking calendar.
That scenario is why the question of what insurance a Connecticut party and tent rental company needs deserves a careful answer. Your exposures are unusual. You're part warehouse operator, part trucking outfit, part construction crew, and part event vendor. A standard small-business package won't cover all of those roles, and insurers know it.
The sections below cover the core lines: liability, property, auto, cyber, and workers' compensation. They also cover the 2026 regulatory changes that affect how your coverage gets placed and priced. If you rent tables and chairs only, some of this won't apply. If you put up structures, most of it will.
Risk Management for Connecticut Rental Businesses
Insurance pays for losses. Risk management keeps them from happening and lowers what you pay. Underwriters who write tent rental accounts look hard at your installation practices before they quote, so your safety program directly affects your premium.
The biggest development this year is industry certification. The American Rental Association fully implemented its Safe Tenting Standard program in early 2026, which uses engineering-backed calculators and installer certifications to professionalize setups. That matters for your wallet. Insurers are increasingly treating the standard as a benchmark for underwriting and premium discounts.
Connecticut adds its own technical requirements. The 2026 State Building Code requires temporary tents erected for up to 60 days to withstand wind speeds of at least 45 mph. If your crew ignores ballast or staking specs and a tent fails below that threshold, expect a claims adjuster and a plaintiff's attorney to focus on that gap.
A practical risk program for a Connecticut rental operation includes:
- Certified installers on every structure job
- Written anchoring calculations kept with each work order
- A documented wind and weather evacuation plan shared with the client
- Photo records of every completed installation
- Signed rental agreements with clear indemnification language
One more local item: the Department of Consumer Protection requires Home Improvement Contractor registration for certain setups exceeding $200. Check whether your residential installs trigger it. An unregistered contractor can complicate both licensing and claim disputes.
General Liability: Protecting Against Tents and Trips
General liability is the policy every venue, municipality, and wedding planner will ask about first. It covers third-party bodily injury and property damage arising from your operations. For your business, that means a guest tripping over a guy line, a collapsed tent injuring attendees, or your truck rutting a client's lawn during delivery.
Cost depends on your mix of business. In 2026, Connecticut party rental businesses typically pay between $2,500 and $5,000 per year for a base general liability policy. Tent installers with large structures usually land at the higher end, while table-and-linen operations sit lower.
The catch is in the policy wording. Watch for these issues that I see trip up rental owners repeatedly:
- Tent or structure exclusions. Some low-cost policies exclude erected structures entirely. If you install tents, this exclusion guts your coverage.
- Inflatable exclusions. Bounce houses are often excluded or sublimited unless specifically scheduled.
- Products-completed operations. Injuries after your crew leaves the site fall here. Confirm this limit isn't reduced.
- Additional insured endorsements. Venues will require them. A blanket additional insured endorsement saves you from requesting certificates job by job.
Here's what that means for you: read the exclusions page before you compare prices. A cheaper quote with a tent exclusion isn't cheaper. It's uninsured.
Commercial Property and Inland Marine Coverage
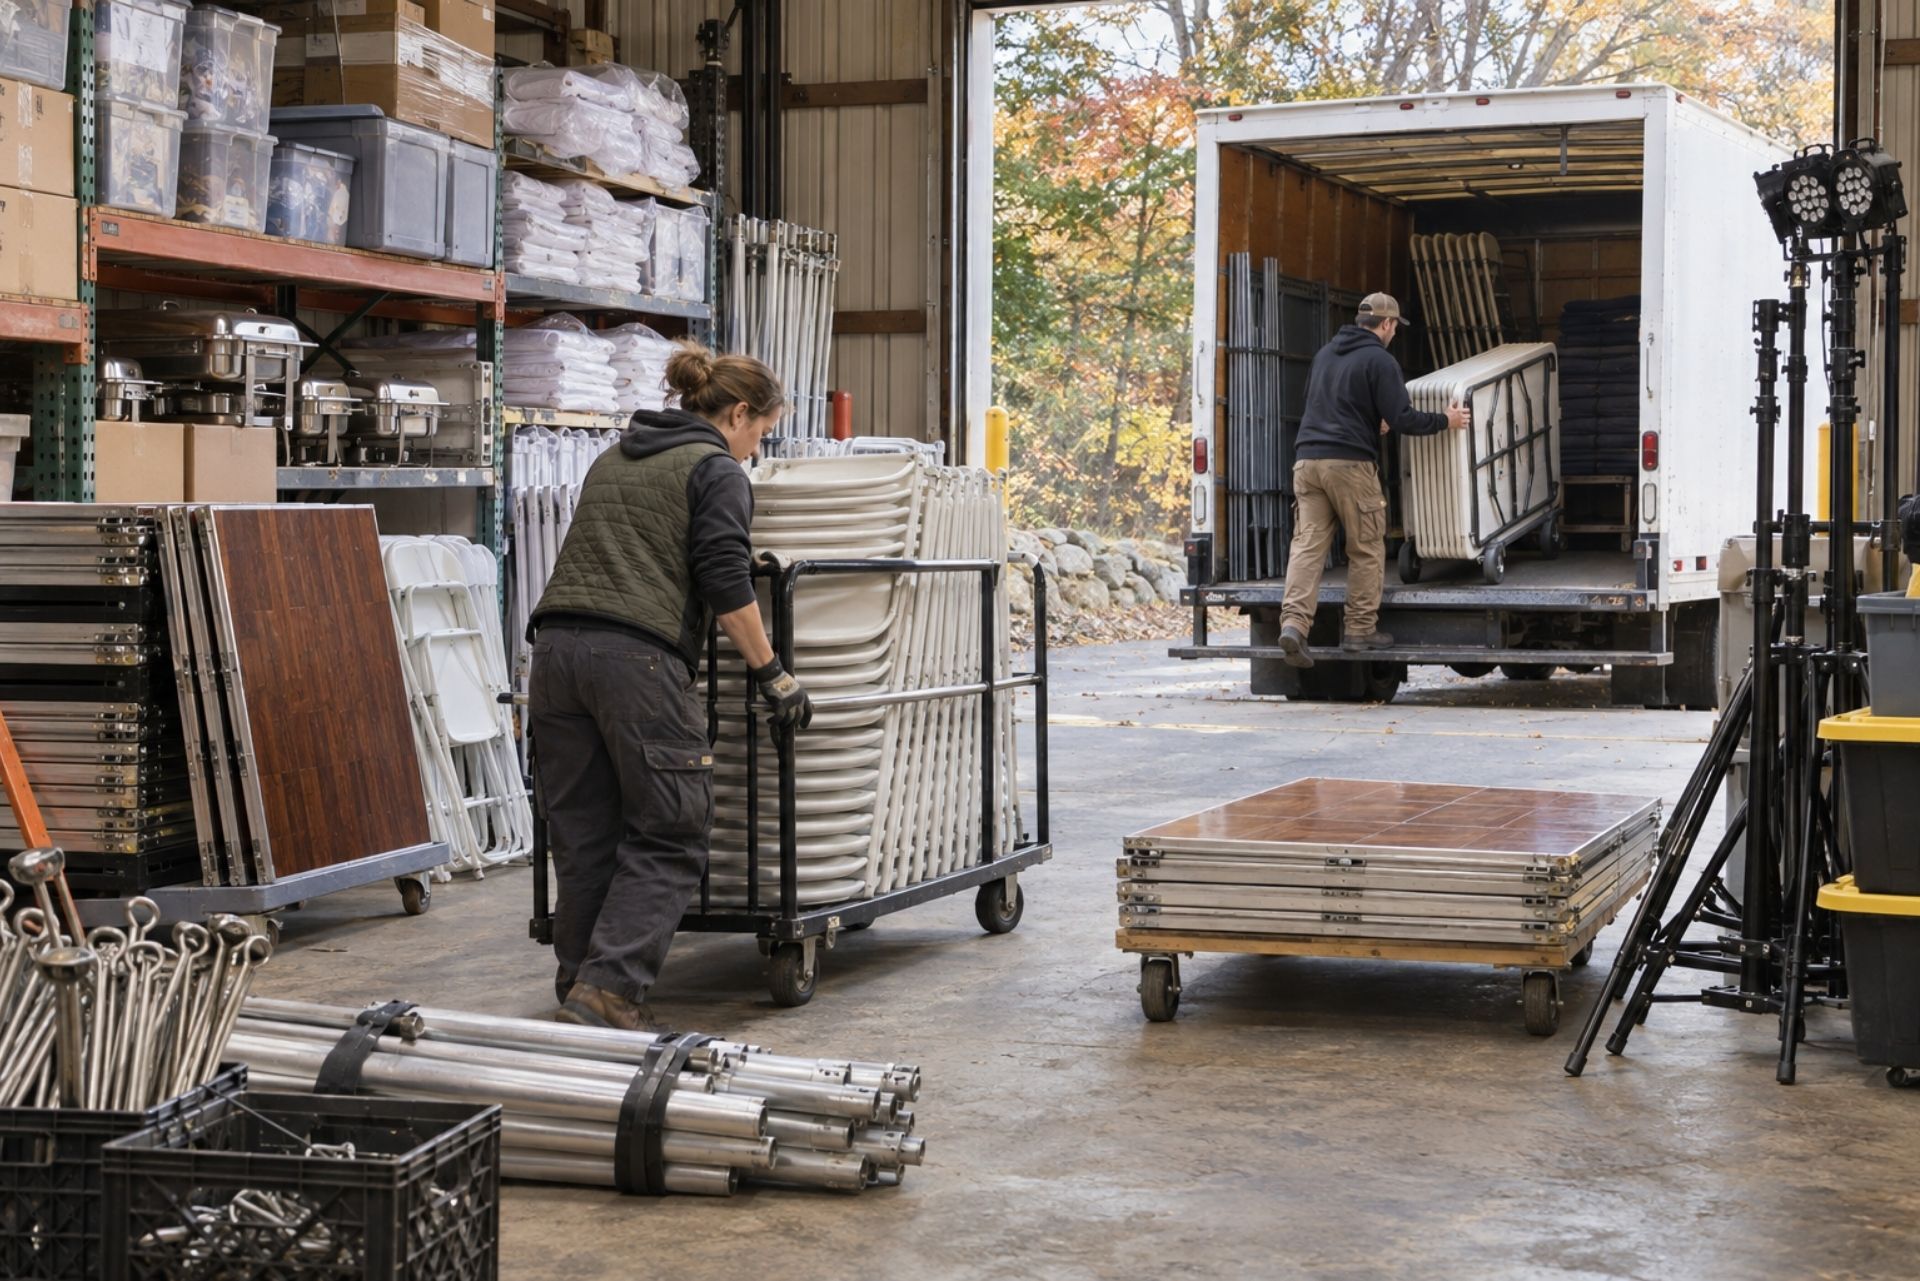
Your inventory is your business. Tents, flooring, staging, lighting, generators, and climate control units represent most of your capital, and they spend much of the year away from your building. Property coverage has to account for both locations.
Insuring Your Warehouse and Inventory
A commercial property policy protects your building, if you own it, plus contents stored there. That includes racked tables, folded tent tops, laundry equipment, and office systems. Insure at replacement cost, not actual cash value. Depreciated payouts on vinyl tent tops won't come close to buying new ones.
Business interruption coverage belongs here as well. Connecticut's event season is compressed, with most revenue arriving between May and October. If a fire or storm destroys inventory in June, you lose the wedding season, not just the equipment. Business income coverage replaces lost profits and pays continuing expenses like payroll and loan payments while you rebuild.
One thing to keep in mind: set your business income limit based on peak-month revenue, not your annual average. Seasonal businesses routinely underinsure this line.
Inland Marine: Protection for Goods in Transit
Standard property insurance usually covers equipment only at your primary business address. Once a tent leaves your yard, it may have no coverage at all. An inland marine policy, often called an equipment floater, follows your property onto trucks and onto event sites.
This coverage responds to losses such as:
- Theft of a generator from an overnight wedding site
- Wind damage to a tent top during an event
- Equipment falling from a trailer on I-95
- Vandalism at a public festival
Schedule high-value items individually and keep serial numbers documented. Ask about the wind deductible too, since some carriers apply a separate, higher deductible for windstorm losses along the shoreline.
Commercial Auto and Workers' Compensation Requirements
Your trucks and your crew create two of your largest exposures. Box trucks loaded with poles and ballast are heavy, crews work long days on tight timelines, and installation involves lifting, climbing, and driving stakes. Claims in these lines tend to be frequent and expensive.
Commercial auto covers liability and physical damage for vehicles your business owns. Personal auto policies typically exclude business use, so an employee hauling trailers in a personal pickup leaves you exposed. Add hired and non-owned auto coverage to protect your business when staff run errands in their own cars or you rent a truck for a busy weekend. Confirm that trailers are listed on the policy, because an unscheduled trailer is a common surprise during a claim.
Connecticut State Mandates for Employees
Connecticut requires most employers with employees to carry workers' compensation insurance. That includes part-time and seasonal workers, which describes much of your summer crew. Workers' comp pays medical bills and lost wages for job-related injuries, and it generally shields you from employee lawsuits over those injuries.
Classification drives your premium. A warehouse worker and a tent installer carry very different rates, and misclassifying installers as clerical or warehouse staff will catch up with you at audit. The same goes for treating crew members as independent contractors. If you control their schedule, tools, and methods, the state will likely view them as employees, and you could owe back premiums and penalties.
Keep accurate payroll records by job duty. At year-end audit, that documentation can legitimately lower your bill.
Cyber Liability and Professional Risks
Rental companies don't think of themselves as tech businesses, but you take deposits online, store client addresses and event dates, and process card payments. A compromised booking system or a phishing email that redirects a client's deposit can cost thousands before you notice.
Cyber liability covers breach response costs, client notification, data restoration, and liability claims tied to exposed information. Many policies also include social engineering coverage, which addresses wire fraud and fake invoice schemes. Confirm that endorsement is included, since it's often the most useful part for a small business and it's frequently sublimited.
Professional risk is the other gap. If you provide layout design, tent sizing advice, or event planning services, a client could claim your recommendation caused a financial loss. Picture a tent that's too small for the guest count or a layout that fails a fire marshal inspection the morning of the event. General liability won't respond to a pure financial loss like that. A professional liability or E&O policy will.
That said, not every rental operator needs E&O. If you simply deliver what the client orders, your exposure is limited. If you consult and design, it's real.
Comparing Coverage: Basic vs. Comprehensive Protection
Many owners start with the minimum a venue demands and add coverage after a loss. That's backward. The table below shows how a basic package compares with a fuller program for a tent and party rental business.
| Coverage Area | Basic Protection | Comprehensive Protection |
|---|---|---|
| General Liability | Base limits, possible tent exclusions | Tents and inflatables included, blanket additional insured |
| Property | Warehouse contents only | Replacement cost plus business income |
| Inland Marine | Often missing | Equipment covered in transit and on site |
| Commercial Auto | Owned vehicles only | Hired, non-owned, and trailers scheduled |
| Workers' Comp | State minimum compliance | Accurate classifications, audit-ready payroll |
| Cyber | None | Breach response plus social engineering |
| Umbrella | None | Excess limits over GL and auto |
Market access has also improved for harder-to-place accounts. Effective October 1, 2026, Connecticut repealed the diligent effort requirement for surplus lines, so brokers can place high-risk rental businesses into the surplus market more efficiently. If standard carriers have declined you over large-structure work or a past claim, that change may speed up your options.
Critical Don'ts Checklist:
- Don't buy general liability without reading the structure exclusions
- Don't assume your property policy covers equipment at event sites
- Don't let employees haul trailers on personal auto policies
- Don't classify installers as contractors to save on premium
- Don't skip business income coverage in a seasonal market
- Don't install tents without documented anchoring calculations
Frequently Asked Questions About Event Rental Insurance
Do I need insurance if I only rent tables and chairs? Yes. Delivery, setup, and a single collapsed chair can lead to an injury claim, so general liability and commercial auto remain essential.
How much does party rental insurance cost in Connecticut? Base general liability typically runs $2,500 to $5,000 per year for Connecticut party rental businesses in 2026. Your full program costs more once you add property, auto, and workers' comp.
Will my policy cover a tent blown down by wind? Damage to your tent falls under inland marine coverage, while injuries to guests fall under general liability. Check for windstorm deductibles and exclusions on both.
Can a safety certification lower my premium? It can. Insurers increasingly use the ARA Safe Tenting Standard as an underwriting benchmark, and some offer discounts for certified operations.
Do seasonal workers need workers' comp? Generally, yes. Connecticut's requirement applies to part-time and seasonal employees as well as full-time staff.
What if standard insurers keep declining me?
Ask a broker about the surplus lines market. Connecticut's 2026 rule change makes those placements faster for high-risk rental accounts.
Making the Right Choice for Your Fleet and Inventory
The right program for your rental company matches how you operate. If you install large frame tents along the shoreline, prioritize liability without structure exclusions, inland marine with sensible wind deductibles, and strong installation documentation. If you run a fleet of box trucks, focus on commercial auto and scheduled trailers. If you take deposits online, add cyber with social engineering coverage.
Connecticut-specific rules shape every one of those choices. The 45 mph wind design requirement for temporary tents, the state's workers' comp mandate, HIC registration for certain residential setups, and the 2026 surplus lines change all affect how you're underwritten and what a claim looks like.
Your next step: pull your current policies and compare them against the comparison table above. Look for exclusions, missing inland marine coverage, and business income limits based on averages rather than peak months. Then sit down with an independent agent who writes rental and event accounts and ask for quotes that reflect your actual operations.
A collapsed tent in July is no time to discover your coverage gaps. Find them now, while the trucks are parked and the season hasn't started.
About The Author:
John F. McGuire
As President of Ferguson & McGuire, I’m committed to helping families and businesses throughout Connecticut find insurance solutions they can trust. With decades of experience in the industry, my focus is on providing personal service, reliable protection, and long-term peace of mind for every client we serve.
GET A QUOTE POPUP
TESTIMONIALS
Business Insurance Client Stories
Business Insurance Solutions in Connecticut
Tailored Assessments for Businesses
We delve into the intricacies of your business operations and insurance requirements, focusing on the specific challenges and opportunities presented by the Connecticut business landscape. Our aim is to identify comprehensive coverage strategies that fully protect your business interests.
Customized Commercial Insurance Solutions
With a keen eye on the unique needs of Connecticut businesses, we craft insurance solutions that precisely match your requirements. Our process is centered around developing the perfect insurance plan that aligns with your business goals and challenges.
Efficient Policy Setup & Ongoing Support
Initiate your selected insurance coverage swiftly, backed by our dedication to offer continuous support for any questions, claims, or adjustments needed. We are committed to keeping you informed and secure, ensuring your business is always prepared and protected.
Commercial Insurance Coverage in Connecticut
General Liability Insurance
Designed for Connecticut businesses, our General Liability Insurance provides essential protection against claims of bodily injury, property damage, and more, ensuring your business is defended against various liabilities.
Workers Compensation Insurance
Tailored for Connecticut businesses, Workers Compensation Insurance covers employee injuries or illnesses occurring on the job, protecting both your employees and your business's financial health.
Professional Liability Insurance
Our Professional Liability Insurance for Connecticut professionals offers extended coverage to protect against claims of negligence or errors in services provided, securing your professional reputation.
Business Owner's Policy (BOP) Insurance
Perfect for Connecticut businesses, our BOP Insurance merges property and liability coverage into a single policy, providing comprehensive protection for your business operations and assets against a multitude of risks.
Cyber Liability Insurance
Aimed at Connecticut businesses in the digital realm, our Cyber Liability Insurance covers risks associated with data breaches, cyber-attacks, and other online threats, ensuring your business's digital assets are protected.
Data Breach Insurance
Specifically for businesses in Connecticut dealing with sensitive information, our Data Breach Liability Insurance offers vital coverage for incidents of data loss or theft, giving you peace of mind in handling digital data.
OUR SERVICES
Explore Our Wide Range of Tailored Insurance Services
FAQs about a credible Connecticut Business Insurance Agency
All About CT Business Insurance: Your Queries Answered
Connecticut Businesses We Serve
Contractor Insurance
Our Contractor Insurance in Connecticut provides General Liability coverage, essential for defending against bodily injury and property damage claims, crucial for your contracting business's resilience and operational continuity.
Bar Insurance
Customized for Connecticut bars, our insurance solutions include Workers Compensation, ensuring employees are covered and your establishment's financial health is maintained in case of job-related injuries or illnesses.
Auto Body Insurance
Connecticut auto body shops benefit from our General Liability Insurance, offering protection against claims of bodily injury and property damage, vital for your business's reputation and financial stability.
Engineers Insurance
Engineers Insurance in Connecticut encompasses Workers Compensation coverage, providing your employees and engineering firm with financial protection against the consequences of workplace injuries or illnesses.
Electricians Insurance
For electricians in Connecticut, our General Liability Insurance is designed to cover occupational risks, including bodily injury and property damage claims, ensuring your business's smooth operation and security.
HVAC Contractors Insurance
HVAC contractors in Connecticut have access to our comprehensive insurance solutions, including Workers Compensation, which covers employee-related injuries or illnesses, maintaining your workforce's well-being and your business's financial health.
Ready to Get Your Business Insured?
Contact Us